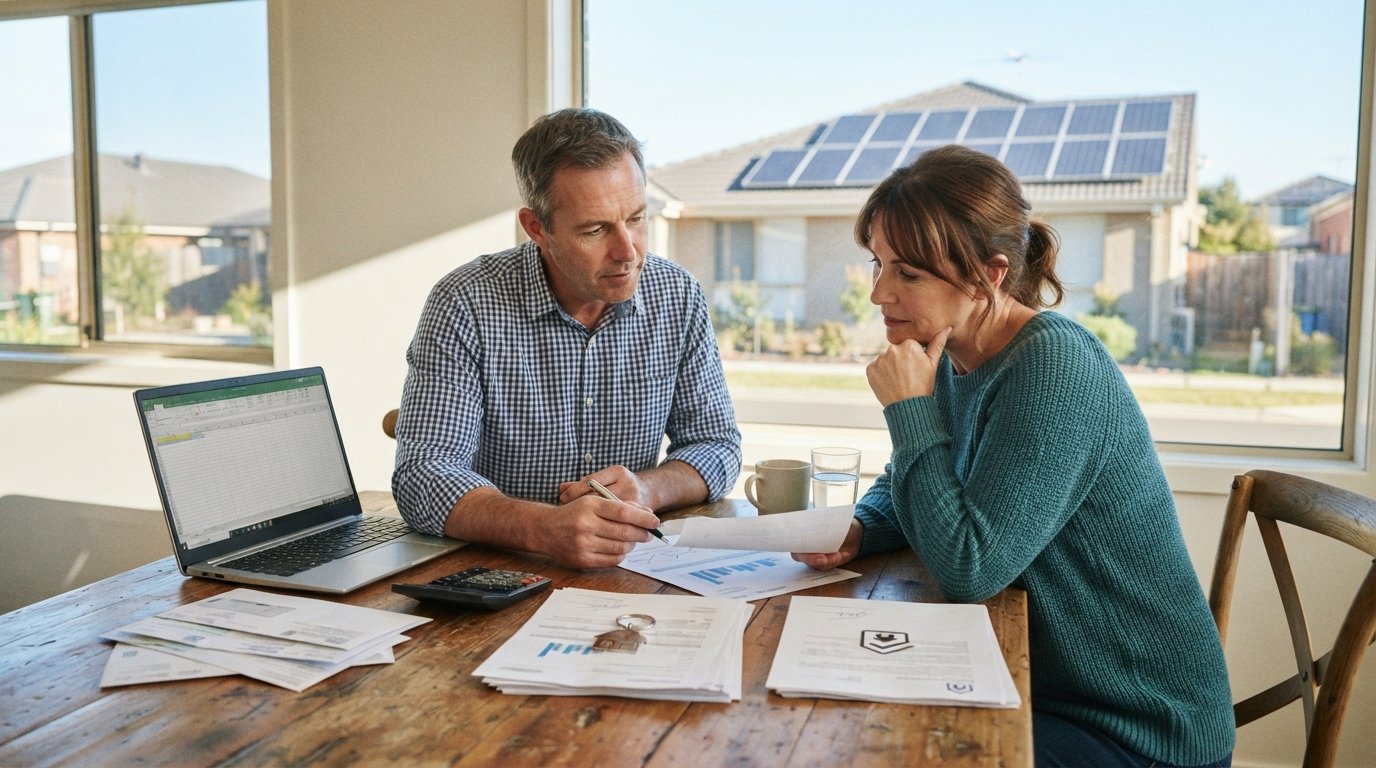
Solar Loan vs PACE Financing for Homeowners
Compare solar loan vs PACE financing for homeowners, from credit checks to home sale impact. Call 8334344023 for expert solar financing guidance.
By Julia Nguyen
Learn more about Solar Panel Installation and Repair for guides, costs, and what to expect.
Compare Solar Panel Installation and Repair Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
Going solar is one of the most impactful investments a homeowner can make, but the financing decision often matters as much as the panels themselves. Two popular options dominate the conversation in 2026: a traditional solar loan and PACE (Property Assessed Clean Energy) financing. Each can get you to the same destination, a rooftop array producing clean power, but they travel very different roads when it comes to credit checks, repayment mechanics, and what happens if you sell your house. Understanding these differences before you sign anything can save you thousands of dollars and a mountain of stress.
How Solar Loans Work in Plain Terms
A solar loan is a personal financing product, usually unsecured or secured by the equipment, that you take out through a bank, credit union, or a lender partnered with your installer. You borrow a set amount to cover the system cost, then repay it over a fixed term, often five to twenty-five years. Because the loan is tied to you rather than your property, the debt stays with you even if you move. That single fact shapes nearly every advantage and drawback of this route.
The monthly payment is predictable. Most solar loans carry a fixed interest rate, so your payment does not change from month to month. Many homeowners pair that payment with their reduced utility bill and find the combined total is lower than what they used to pay the electric company alone. A typical structure looks like this:
- Loan amount equals the full installed system cost, minus any rebates applied at closing.
- Fixed interest rates commonly range from roughly 4% to 9% depending on credit and term.
- Terms stretch from 5 to 25 years, with 10 to 15 years being the most common.
- Some lenders offer a re-amortization feature after you receive the federal tax credit, lowering your payment.
Solar loans generally require a credit check and a debt-to-income review, which means your credit score directly affects your rate. Homeowners with strong credit often secure the lowest rates and pay the least over the life of the loan. Those with weaker credit may face higher rates or need a co-signer.
Another key feature is ownership. Because you bought the system outright with borrowed money, you own the equipment from day one. That ownership unlocks the federal Investment Tax Credit, currently 30% of the system cost for eligible installations, plus any state or utility incentives. It also means you are responsible for maintenance and repairs, though most systems require very little beyond occasional cleaning and monitoring.
What PACE Financing Actually Is
PACE financing works completely differently. Instead of lending you money as an individual, a PACE program funds your solar installation through a special property tax assessment attached to your home. You repay it through your annual property tax bill, usually in semi-annual installments, over a term that can run 10 to 25 years. The debt is tied to the property, not to you personally, which is the defining characteristic of this model.
Because PACE is assessed against the property, many programs do not run a traditional credit check. Approval is often based on home equity and a history of on-time property tax payments. That opens the door for homeowners who might struggle to qualify for a conventional loan, including retirees on fixed incomes or self-employed borrowers with irregular income documentation.
PACE programs exist in a patchwork of states and municipalities across the country, and availability varies widely. California, Florida, Missouri, and a handful of other states have robust residential PACE markets, while many states have no residential PACE option at all. Even where PACE exists, individual counties and cities must opt in, so two neighbors in the same state can face very different options.
The repayment structure also differs in a subtle but important way. PACE assessments are typically fixed-rate and paid alongside your property taxes. If you fall behind, the consequences attach to your property tax status, which can be severe, including tax liens and, in extreme cases, foreclosure. That is a meaningful risk that a standard unsecured solar loan does not carry in the same form.
Solar Loan vs PACE Financing for Homeowners: A Side-by-Side Comparison
When homeowners weigh solar loan vs PACE financing for homeowners, the decision usually comes down to five practical factors: approval requirements, total cost, impact on a home sale, tax treatment, and flexibility. Seeing them side by side makes the trade-offs much clearer.
- Credit requirements: Solar loans require a credit check and income verification. PACE typically does not, relying instead on home equity and property tax history.
- Cost over time: Solar loans often carry lower interest rates for borrowers with good credit. PACE rates can be higher and are sometimes bundled with program fees that are less transparent.
- Impact on selling your home: A solar loan must be paid off or assumed at sale. A PACE assessment transfers with the property, which can complicate or delay a sale if buyers or their lenders object.
- Tax treatment: Solar loan interest may be deductible if the loan is structured as a home improvement loan and you itemize. PACE assessments are paid through property taxes and may be deductible as property tax, subject to the SALT cap.
- Ownership and incentives: Both routes let you own the system and claim the federal tax credit, provided you have sufficient tax liability to use it.
The selling point is where PACE and solar loans diverge most dramatically. PACE was designed with the idea that the assessment stays with the property, so a new buyer simply takes over the remaining payments. In practice, many buyers and mortgage lenders are wary of assuming a PACE obligation. Some conventional mortgage lenders treat PACE as a subordinate lien and may require it to be paid off before approving a new loan. That can force a seller to settle the balance at closing, sometimes wiping out the equity they expected to walk away with.
Solar loans, by contrast, are personal debts. When you sell, you either pay off the remaining balance from the proceeds or negotiate for the buyer to assume the loan. This is usually more straightforward because the debt is independent of the property title. It also means the loan does not automatically burden the next owner, which many buyers prefer.
Total Cost and Long-Term Value
Cost comparisons between solar loans and PACE financing are rarely apples to apples. Solar loans advertise an interest rate, and that rate is the primary cost. PACE programs often advertise a rate too, but the true cost can include origination fees, administrative fees, and the fact that the assessment appears on your property tax bill, where it can be easy to overlook.
Over a 20-year term, a one-percentage-point difference in rate on a $25,000 system translates to roughly $2,000 to $3,000 in extra interest. That is real money, and it is why homeowners with decent credit usually find solar loans more economical. PACE can still make sense for borrowers who cannot qualify for a loan, or who value the no-credit-check convenience and plan to stay in the home long enough to realize the savings.
One more financial angle deserves attention: the federal tax credit. Both financing routes allow you to claim the 30% credit if you own the system and have tax liability to offset. PACE and solar loan payments themselves are not eligible for the credit, only the equipment and installation costs. Homeowners who cannot use the full credit in one year should plan how to carry it forward, because the credit can be applied to future tax years.
For a deeper look at how technology is changing the economics of home solar, including how AI monitoring can squeeze more value from every panel, see this guide on how AI improves home solar efficiency. Better monitoring does not change your financing, but it can improve the return on whichever option you choose.
Which Option Fits Which Homeowner
The right choice depends less on the product and more on your personal financial picture. A homeowner with a 750 credit score, stable income, and plans to stay put for a decade will almost always come out ahead with a solar loan. The lower rate, the clean ownership, and the simple exit at sale make it the default recommendation.
PACE tends to appeal to a different profile: someone who has significant home equity but limited access to conventional credit, or who wants to avoid a credit inquiry altogether. It can also suit homeowners in states with strong PACE programs and consumer protections, where the assessment is well regulated and the fees are transparent.
Before committing to either path, it helps to compare quotes from multiple installers and lenders. A free quote comparison can reveal that one installer offers a better loan rate while another has a stronger PACE program. Taking an hour to gather three or four quotes often saves more than any single negotiation tactic. Homeowners exploring their options can start by connecting with vetted professionals through NewSolarQuotes, an independent resource that helps consumers compare renewable energy providers and understand their financing choices.
It also pays to read the fine print on both products. Solar loan contracts should disclose the APR, any origination fees, and whether the rate is fixed or variable. PACE contracts should disclose the total assessment amount, the annual percentage rate, the term, and exactly what happens if you sell or refinance. If a salesperson cannot or will not provide those numbers in writing, that is a red flag regardless of which product they are pushing.
Questions to Ask Before You Sign
Whether you lean toward a loan or PACE, a short list of questions will protect you. Ask each lender or program administrator the same questions and compare the answers directly.
- What is the total amount I will repay over the full term, including all fees?
- Is the rate fixed for the entire term, or can it change?
- What happens to this obligation if I sell my home before the term ends?
- Does this financing affect my ability to refinance or take out a home equity line later?
- Are there penalties for paying off the balance early?
The answers often reveal that a product marketed as simple is anything but. PACE, in particular, can complicate a future refinance because mortgage lenders may treat the assessment as a lien that must be cleared. A solar loan, while it affects your debt-to-income ratio, does not attach to the property title and therefore poses fewer complications for a future mortgage transaction.
It is also wise to run the numbers with a solar savings calculator before choosing a financing route. The calculator will show your estimated monthly savings, payback period, and return on investment, which you can then compare against the monthly payment for each financing option. The option that keeps your combined payment below your current electric bill while maximizing long-term savings is usually the winner.
The Bottom Line for Homeowners
Solar loan vs PACE financing for homeowners is not a contest with a single winner. It is a matchup between two tools designed for different situations. Solar loans reward good credit with lower rates and simpler exits, while PACE opens the door for homeowners who value no credit checks and are comfortable with a property tax assessment. The smartest move is to get quotes for both, read every disclosure, and choose the option that keeps your total monthly cost low and your future flexible. With the right financing in place, your solar investment can deliver decades of clean, affordable power.