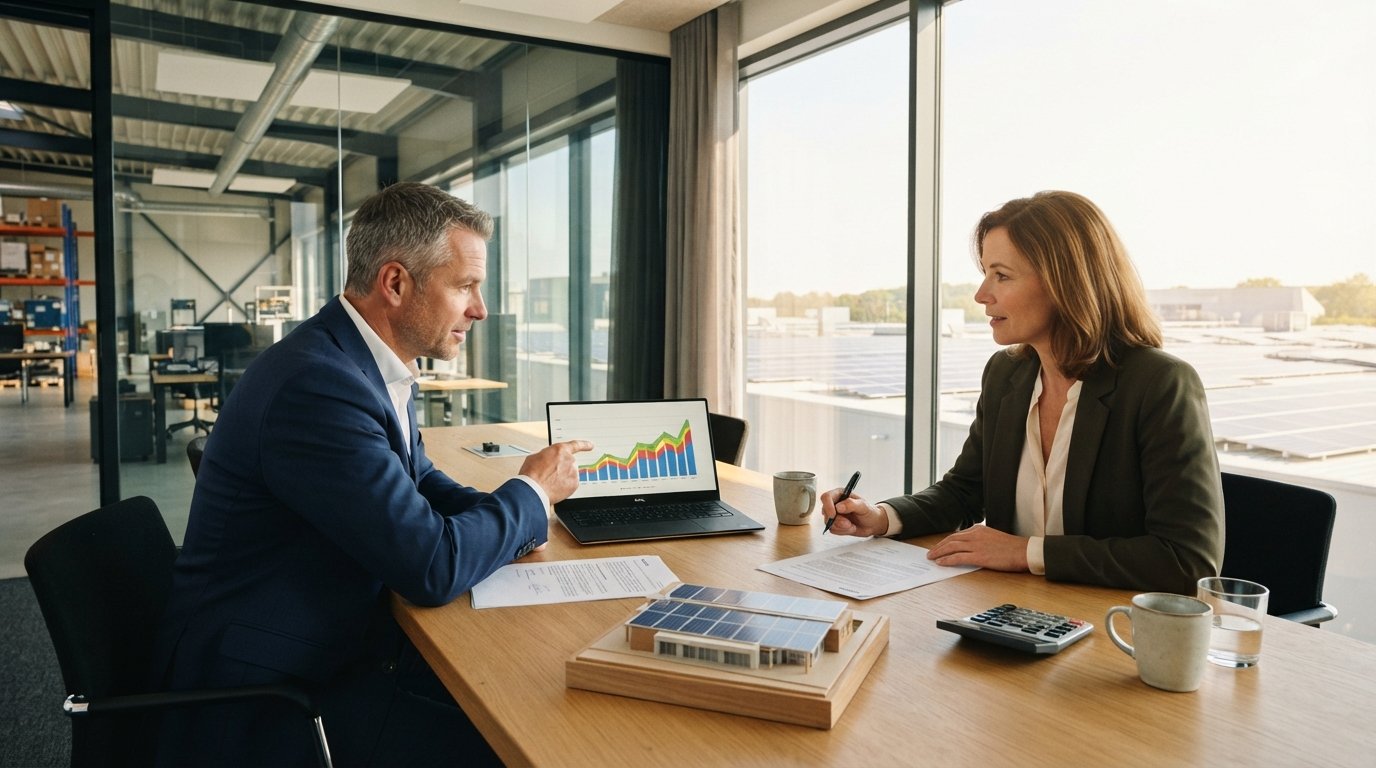
Commercial Solar Financing Loans vs Power Purchase Agreements
Compare commercial solar financing loans vs power purchase agreements to find the best fit for your business cash flow and tax position.
By Mason Carter
Learn more about Solar Panel Installation and Repair for guides, costs, and what to expect.
Compare Solar Panel Installation and Repair Pros Near You
Enter your ZIP code to compare top-rated local professionals and request free quotes.
Business owners evaluating commercial solar often face a deceptively simple question: should you buy the system outright with a loan, or sign a power purchase agreement and let a third party own the hardware? The answer shapes your cash flow, tax position, and long-term energy costs for decades. Unlike a residential rooftop decision, commercial solar financing involves depreciation schedules, ITC allocation, and complex contract terms that can swing total project value by hundreds of thousands of dollars.
This guide breaks down commercial solar financing loans vs power purchase agreements with real numbers, contract mechanics, and decision frameworks you can apply to your own facility. Whether you operate a warehouse in Phoenix, a retail chain across the Southeast, or a manufacturing plant in the Midwest, the same core tradeoffs apply: who owns the asset, who claims the incentives, and who absorbs the performance risk.
How Commercial Solar Loans Work
A commercial solar loan is a debt instrument secured against the system, your property, or your business credit. You own the panels, inverters, and racking from day one. That ownership unlocks the federal Investment Tax Credit, accelerated depreciation under MACRS, and any state or utility rebates. You also capture the full value of every kilowatt-hour the system produces, minus loan payments.Most lenders structure commercial solar loans with terms between 5 and 25 years. Interest rates vary widely based on creditworthiness, collateral, and whether the loan is secured or unsecured. A strong commercial borrower might see rates in the 6 to 9 percent range, while a small business with thinner credit could face double-digit APRs. Some lenders offer stepped payment structures where early years carry lower payments, aligning with the solar system's production ramp and your own revenue cycles.
The key advantage is control. You decide when to clean the panels, which inverter to install, and whether to add battery storage later. You also capture the residual value of the system after the loan is paid off, which for a 25-year asset can mean another decade or more of essentially free electricity. If you want to understand how ownership compares to leasing in a broader context, our guide on commercial solar lease vs purchase walks through similar tradeoffs from a different angle.
How Power Purchase Agreements Work
Under a commercial solar power purchase agreement, a third-party developer owns the system on your roof or land. You sign a long-term contract, typically 15 to 25 years, to buy the electricity the system produces at a fixed or escalating rate per kilowatt-hour. That rate is usually set below your current utility rate, often with an annual escalator of 1 to 3 percent.
The developer handles design, permitting, installation, maintenance, and insurance. You write a check only for the power you consume, which means zero upfront capital expenditure. For businesses that cannot use the tax credits, either because they are nonprofits, schools, or have low tax liability, a PPA can unlock solar savings that would otherwise be inaccessible.
The tradeoff is that you never own the system. The developer claims the ITC and depreciation. You are locked into a long-term contract with early termination provisions that can be expensive. If your facility's energy needs change dramatically, or if you sell the building, the PPA becomes a liability that must be assigned or bought out.
Comparing Cash Flow and Total Cost of Ownership
To make a smart decision, you need to model both options side by side using your actual utility rate, your tax situation, and your expected holding period. Here is a simple framework:
- Estimate annual production in kilowatt-hours using a tool like the Solar Savings Calculator or a site-specific production model from an installer.
- Calculate the loan scenario: subtract annual loan payments from the value of electricity produced, then add the ITC and depreciation benefits in years one through six.
- Calculate the PPA scenario: multiply annual production by the PPA rate, then compare that cost to what you would have paid the utility.
- Run a net present value analysis over your expected ownership horizon, typically 10 to 25 years.
In many cases, a loan produces higher total savings over the life of the system because you capture the incentives and the residual value. A PPA produces lower savings but requires no capital and shifts performance risk to the developer. The right answer depends on whether you value maximization or simplicity.
Consider a mid-sized distribution center with a $1.2 million solar project. A 10-year loan at 7 percent might cost roughly $170,000 per year. The system might produce $220,000 worth of electricity annually, plus a $360,000 ITC in year one and depreciation benefits worth another $250,000 over several years. The PPA alternative might charge $180,000 per year for the same electricity, with no incentives and no ownership. Over 25 years, the loan scenario can be worth several hundred thousand dollars more, but it requires the business to have the tax appetite and balance sheet to carry the debt.
Tax Implications and Incentive Capture
The federal Investment Tax Credit is the single largest incentive for commercial solar, covering 30 percent of project cost for systems placed in service through at least 2032. Under a loan or cash purchase, your business claims that credit directly against tax liability. Under a PPA, the developer claims it and passes through a portion of the value in the form of a lower electricity rate.
Depreciation is equally important. Commercial solar systems qualify for five-year MACRS depreciation, and bonus depreciation may allow you to write off a significant portion of the basis in year one. For a profitable business, these deductions can be worth 20 to 30 percent of project cost in present-value terms. If your business has no tax liability, those benefits are wasted unless you use a tax equity structure or a PPA.
State and local incentives add another layer. Some states offer grants, rebates, or property tax exemptions for commercial solar. Under a PPA, the developer typically captures these incentives and factors them into your rate. Under a loan, you capture them directly. Always verify current incentive availability with your state energy office or a qualified tax advisor, because programs change frequently.
Risk, Maintenance, and Operational Control
Ownership means responsibility. With a loan, you are responsible for maintenance, insurance, inverter replacement, and panel cleaning. Those costs are real but manageable, typically 1 to 2 percent of project cost per year. You also bear the risk of underperformance. If the system produces less than expected, you still owe the loan payment.
A PPA shifts that risk to the developer. Most PPAs include performance guarantees, and the developer is incentivized to keep the system running at peak output because their revenue depends on production. You do not need to budget for inverter replacements or emergency repairs. For businesses without an energy manager on staff, that operational simplicity can be worth the lower total savings.
Control also matters for future planning. If you want to add battery storage, EV charging, or a microgrid, owning the system gives you flexibility. If you are under a PPA, you may need the developer's consent to modify the system or add equipment. Review contract terms carefully before signing.
When a Commercial Solar Loan Makes Sense
A loan is often the better choice when your business has steady taxable income, a strong balance sheet, and a long-term horizon on the property. You can use the ITC and depreciation to offset other tax liabilities, and you capture the full value of the system over its 25 to 30 year life. If you plan to own the building for at least 10 years, the math usually favors ownership.
Loans also make sense if you want to bundle solar with other capital improvements, such as a new roof or electrical panel upgrade. Lenders may offer combined financing, and owning the system simplifies the accounting and insurance picture. Finally, if your utility rate is high and rising, locking in a fixed loan payment while electricity rates climb can produce a powerful hedge against future cost increases.
When a Power Purchase Agreement Makes Sense
A PPA is often the better choice when your business cannot use the tax credits, when capital is tight, or when you want predictable energy costs without operational responsibility. Nonprofits, schools, municipalities, and churches frequently use PPAs because they have no tax liability to offset. Businesses with leased facilities may also prefer a PPA if the landlord is unwilling to finance a solar system.
PPAs can also be attractive if you are uncertain about how long you will occupy the building. Some contracts allow assignment to a new tenant or buyer, though terms vary. If your credit is weak or your balance sheet is leveraged, a PPA may be the only way to access solar savings without taking on additional debt.
For businesses exploring renewable energy options beyond solar, resources like NewSolarQuotes provide educational guides and cost calculators that cover hydropower and wind as well as solar. Comparing technologies can help you decide whether solar is the right first step or whether a hybrid approach makes more sense.
Key Contract Terms to Negotiate
Whether you choose a loan or a PPA, the contract details determine whether the deal works for you. Here are the terms that matter most:
- Loan terms: interest rate, term length, prepayment penalties, collateral requirements, and whether the loan is recourse or non-recourse.
- PPA terms: rate per kilowatt-hour, escalator, term length, production guarantee, early termination buyout, and assignment rights.
- Both: who owns the renewable energy credits, how net metering or excess production is credited, and what happens if you sell the building.
Negotiate hard on these points. A 1 percent difference in a PPA escalator or a 2 percent difference in a loan rate can change total project value by tens of thousands of dollars. Bring in a financial advisor or attorney who has experience with commercial solar transactions.
Making the Decision: A Practical Framework
Start by answering three questions. First, can your business use the federal ITC and depreciation in the year the system is placed in service? If yes, ownership via loan or cash purchase is usually more valuable. Second, how long will you own or occupy the building? If less than seven years, a PPA may be easier to transfer. Third, how much operational risk are you willing to accept? If you want a hands-off solution, a PPA shifts that burden to the developer.
Once you have those answers, model both scenarios with real numbers. Use your actual utility rate, your marginal tax rate, and your cost of capital. Compare net present value, cash flow in each year, and total savings over your holding period. The option with the highest risk-adjusted return is the one that fits your business.
Commercial solar financing loans vs power purchase agreements is not a one-size-fits-all choice. It is a strategic decision that depends on your tax position, your balance sheet, and your long-term plans for the property. Take the time to run the numbers, negotiate the contract, and consult professionals who understand both structures. The right financing can turn a solar project from a cost center into a decades-long profit driver.